

Don't want to trade it yourself?
Our desk runs DEX portfolios on profit share.
- Deutsche Bank has recently issued and announced multiple fixed rate, callable Eurodollar notes across maturities from 2031 to 2051, while its New York entities raised the prime lending rate to 7.00% from 6.75% on 17 September 2026.
- The bank is also preparing to launch regulated cryptocurrency custody for institutional clients, which shifts its operating mix further toward digital asset services and fee-based income streams.
- This article examines how Deutsche Bank’s investment narrative is affected by the move into institutional crypto custody services.
Scan how Deutsche Bank’s crypto custody pivot compares with other financial institutions pushing into digital assets by reviewing a curated 18 cryptocurrency and blockchain stocks that are already building out this theme.
Deutsche Bank Investment Narrative Recap
To own Deutsche Bank, you generally need to believe the institution can keep turning a large, complex balance sheet into steady fee and interest income while managing credit, legal and regulatory pressures. The near term story revolves around execution on digitalisation and higher margin services such as crypto custody, without losing discipline on costs or capital.
The biggest swing factor in the short run is still asset quality and funding costs, especially with exposure to higher risk loans and external wholesale funding. The latest fixed income and prime rate moves do not materially change those core risks, but they do slightly reshape the mix of funding and interest earnings.
The most relevant recent step is the string of fixed rate Eurodollar offerings, such as the 6.50% notes due 2041 and the 6.05% notes due 2051. This funding sits alongside customer deposits and helps support lending, trading and new services like institutional crypto custody, while locking in known coupons for the bank.
For you as a shareholder, the focus is on execution risk and flexibility. Callable, unsecured senior notes across 2031 to 2051 create optionality if funding conditions improve, yet they also add to wholesale liabilities. That detail matters when considering credit risk, regulatory demands and how comfortably Deutsche Bank can pursue fee heavy growth themes without straining its balance sheet.
What The Crypto Pivot Assumes About Deutsche Bank’s Numbers
Deutsche Bank’s narrative projects €35.9 billion revenue and €7.4 billion earnings by 2029. This implies 5.6% yearly revenue growth and an earnings increase of about €1.3 billion from €6.1 billion today.
Those forecasts sit in the background when you think about the move into institutional crypto custody. Analysts are not breaking out digital asset services separately in these figures, but the story still hinges on the same basic question for you as an investor: Can the bank turn higher fee businesses, including digital custody and trading related services, into that extra €1.3 billion of profit while keeping risk in check?
The revenue growth rate of 5.6% a year over the next three years assumes more than just higher lending volumes. It implies a heavier mix of recurring commissions and service fees, where secure storage and servicing of crypto assets for institutions could play a role alongside wealth management and transaction banking. If those fee pools scale more slowly than expected, the headline revenue number of €35.9 billion by 2029 would be harder to reach using the current product set.
On the earnings side, the move from €6.1 billion today to €7.4 billion in 2029 also leans on a margin shift. Profitability is assumed to move from 20.0% to 20.7%, which is not a huge jump on paper. For that modest uplift to hold, Deutsche Bank needs crypto custody, payments and related digital services to come with decent pricing power and tightly managed operating costs, rather than heavy up front investment that drags on returns.
Institutional crypto storage is capital light compared with traditional lending. That characteristic matters for a bank that analysts expect to trade on a P/E of 9.9x on 2029 earnings versus 10.0x today. If the custody business helps Deutsche Bank lean further into capital light income streams, it can support that earnings path without putting extra strain on regulatory capital or wholesale funding structures such as the Eurodollar notes discussed earlier.
The forecasts also build in a slow reduction in the share count, with analysts expecting outstanding shares to decline by 1.67% per year. That expectation links back to digital projects such as crypto custody in a practical way. Management needs those initiatives to generate enough incremental and relatively stable earnings to support ongoing buybacks or similar capital returns, while still funding technology spend, compliance and risk management around digital assets.
For you, these figures give a rough yardstick. Any assessment of Deutsche Bank’s crypto custody push needs to be measured against the implied €35.9 billion top line and €7.4 billion bottom line in 2029, plus the required 5.6% annual revenue climb and slightly higher margins. The closer the real world economics of institutional digital asset services get to those embedded assumptions, the more coherent the overall investment narrative looks.
Discover why Deutsche Bank’s fair value is essentially in line with its current price.
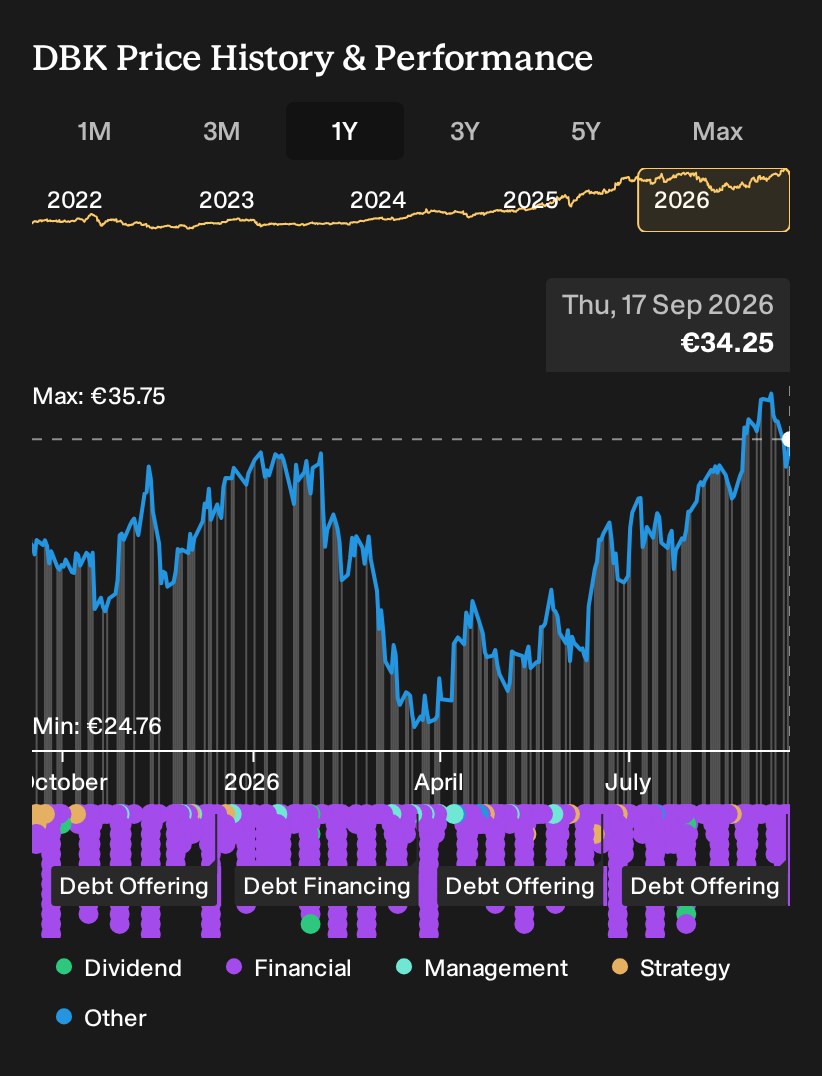
Exploring Other Perspectives
Pessimistic analysts focus on balance sheet risk. You see them worry that issuing long dated 5% to 6.5% notes adds funding cost just as digital rivals pressure pricing. Before this news, the bullish camp still pencilled in €38.3b revenue and €9.6b earnings by 2029, far above consensus. Opinions already span a wide range and may shift again as Deutsche Bank’s crypto custody plans and new bond deals play through.
Explore 4 other Deutsche Bank fair value estimates, including one that suggests as much as 76% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Deutsche Bank research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Deutsche Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Deutsche Bank’s overall financial health at a glance.
Looking For More Investment Ideas Beyond Deutsche Bank?
If the Deutsche Bank story has sharpened your thinking about risk, income and long term potential, it often helps to compare it with a broader watchlist of opportunities that fit different goals.
- If you want potential mispricing with quality traits, use our screener highlighting 173 high quality undervalued stocks that already show solid fundamentals.
- If resilience matters more to you than pace of returns, focus on companies in the screener featuring 227 resilient stocks with low risk scores with more measured risk profiles.
- If you prefer strong finances as a starting point, scan the screener built around a list of solid balance sheet and fundamentals (196 results) that can support growth or steady dividends through a range of conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New:Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
The rate hike just raised the bar every company you own has to clear before spending.
If inflation is coming from an energy shock and a supply squeeze, what does an overnight rate do about it? You cannot raise rates at a pipeline.
Constellation Software is one of my favorite capital allocators.

Mitchell Lawler
Market Insights
What happens to energy stocks as the fix gets built?

Conflict around the Strait of Hormuz has led investors to oil and tankers. The trouble is, the antidote to the chokepoints is already being built, and it may not reward the same energy stocks.
00
Sep 18, 2026
About XTRA:DBK
Deutsche Bank
A stock corporation, provides corporate and investment banking, private clients, and asset management products and services in Germany, the United Kingdom, the rest of Europe, the Americas, the Asia-Pacific, the Middle East, and Africa.
Undervalued average dividend payer.
Similar Companies
-
NasdaqGM:QQQ
Invesco QQQ Trust Series 1
-
Morgan Stanley
Market Insights
What happens to energy stocks as the fix gets built?MI
Mitchell Lawler
Are social media stocks the new Big Tobacco?AN
Andrew Legget
What 13F filings won’t tell you about a billionaire’s stock picksMI
Mitchell Lawler
Advertisement
Weekly Picks

Ceazaron Sparc AI·22 days ago
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2530.5% undervalued
200followersusers have followed this narrative
·0commentsusers have commented on this narrative
·31likesusers have liked this narrative
CO

composite32on Archrock·9 days ago
AI Needs Power. Power Needs Gas. Gas Needs Compression: The Archrock Investment Thesis
Fair Value:US$44.8830.4% undervalued
27followersusers have followed this narrative
·2commentsusers have commented on this narrative
·3likesusers have liked this narrative
JO

John_Ericon Advanced Energy Industries·18 days ago
AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor.
Fair Value:US$567.8655.2% undervalued
16followersusers have followed this narrative
·0commentsusers have commented on this narrative
·7likesusers have liked this narrative
IS

isidrohgon Lam Research·7 days ago
The Memory Shortage Is Lam’s Order Book
Fair Value:US$423.8536.5% undervalued
23followersusers have followed this narrative
·0commentsusers have commented on this narrative
·7likesusers have liked this narrative
RecentlyUpdated Narratives

John_Ericon Viper Energy·about 1 hour ago
Everyone Else Drills the Wells. Viper Just Collects the Checks.
Fair Value:US$113.3462.1% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
RE

RedCandleRxon Celsius Holdings·about 4 hours ago
Celsius Holdings: Undervalued Growth Opportunity Or Trap?
Fair Value:US$4130.9% undervalued
2followersusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
LU

LunaRodason Upexi·about 6 hours ago
UPXI | Upexi, Inc.: What They Said vs. What They Did
Fair Value:US$1.841.5% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives

AnalystConsensusTargeton NVIDIA·about 2 months ago
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.6% undervalued
1465followersusers have followed this narrative
·8commentsusers have commented on this narrative
·35likesusers have liked this narrative
AN

AnalystConsensusTargeton Alphabet·4 months ago
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8918.8% undervalued
1639followersusers have followed this narrative
·0commentsusers have commented on this narrative
·19likesusers have liked this narrative
AN

AnalystConsensusTargeton Amazon.com·about 1 month ago
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.2% undervalued
1650followersusers have followed this narrative
·1commentusers have commented on this narrative
·16likesusers have liked this narrative
Source: simplywall.st
1 Comment
Pingback: Franklin Templeton (BEN) Pushes Further Into Blockchain, Is The Stock Still Cheap? – xpertsstudio